NepalHRM
Free PF Calculator

PF Calculator Nepal: 10% + 10% of Basic

Enter a basic salary and read the Provident Fund (सञ्चय कोष) contribution from the employee and the employer, monthly and yearly, what the account could hold after a number of years, and what the deduction does to income tax. Every line of the working is shown.

  • Assessed on basic salary
  • No sign-up
  • Working shown

Nepal PF rates

Employee, deducted from pay
10%
Employer, paid on top
10%
Of basic deposited each month
20%
Yearly cap on the tax deduction
NPR 500,000
Rate:
Employee (10%)NPR 3,000a month · NPR 36,000 a year
Employer (10%)NPR 3,000a month · NPR 36,000 a year
Total to PF (20%)NPR 6,000a month · NPR 72,000 a year
Balance from deposits after 10 yearsNPR 720,000
Deposited
NPR 720,000
Interest
NPR 0
Rate used
0%

Deposits only, with no interest assumed. The Employees Provident Fund adds the interest it declares each year, so the real balance will be higher than this.

Retirement deduction and income tax, FY 2083/84
Your PF for the year, both shares
NPR 72,000
Assessable income (gross × 12 + employer PF)
NPR 636,000
Income test (assessable income ÷ 3)
NPR 212,000
Fixed ceiling
NPR 500,000
Deduction allowed, the lowest of the three
NPR 72,000
Taxable income
NPR 564,000
Income tax for the year
NPR 5,640 (NPR 470 a month)
With no PF on either side
NPR 6,000
Tax saved by PF this year
NPR 360

Gratuity is separate from PF: NPR 2,499 a month on this basic, under Labour Act 2074 Section 53(1). It is not part of the PF deposit and is not in the balance above. The tax side follows the salary tax calculator: the employer's 10% counts as your income and as a contribution, so both shares count against the limit.

Show the working

Contributions

  1. Employee PF: NPR 30,000 × 10% = NPR 3,000 a month, deducted from salary (Labour Act 2074 Section 52(1))
  2. Employer PF: NPR 30,000 × 10% = NPR 3,000 a month, paid on top of salary
  3. Deposited: NPR 3,000 + NPR 3,000 = NPR 6,000 a month, and NPR 6,000 × 12 = NPR 72,000 a year

Balance

  1. Balance after 10 years: NPR 72,000 × 10 = NPR 720,000, deposits only, with no interest assumed

Income tax

  1. Your PF for the year: NPR 36,000 yours + NPR 36,000 the employer's = NPR 72,000
  2. Assessable income: NPR 600,000 gross + NPR 36,000 employer PF, which counts as your income (Income Tax Act 2058 Section 8(2)(f)) = NPR 636,000
  3. Income test: NPR 636,000 ÷ 3 = NPR 212,000
  4. Fixed ceiling: NPR 500,000 (Income Tax Act 2058 Section 63)
  5. Deduction: the lowest of the three, NPR 72,000
  6. Taxable income: NPR 636,000 − NPR 72,000 = NPR 564,000
  7. Income tax on that at the FY 2083/84 slabs: NPR 5,640 a year, NPR 470 a month in TDS
  8. With no PF on either side the tax on the gross alone would be NPR 6,000, so PF saves NPR 360 in tax this year

Gratuity

  1. Gratuity: NPR 30,000 × 8.33% = NPR 2,499 a month (Labour Act 2074 Section 53(1)). A separate benefit: it is not part of the PF deposit and is not in the balance above
Year by year
YearBrought forwardDepositedInterestBalance
1NPR 0NPR 72,000NPR 0NPR 72,000
2NPR 72,000NPR 72,000NPR 0NPR 144,000
3NPR 144,000NPR 72,000NPR 0NPR 216,000
4NPR 216,000NPR 72,000NPR 0NPR 288,000
5NPR 288,000NPR 72,000NPR 0NPR 360,000
6NPR 360,000NPR 72,000NPR 0NPR 432,000
7NPR 432,000NPR 72,000NPR 0NPR 504,000
8NPR 504,000NPR 72,000NPR 0NPR 576,000
9NPR 576,000NPR 72,000NPR 0NPR 648,000
10NPR 648,000NPR 72,000NPR 0NPR 720,000

Three worked examples

The same arithmetic as the calculator, written out. Rates from 10% + 10% of basic, the tax side on the FY 2083/84 slabs.

The minimum basic remuneration, 10 years

NPR 12,170 basic and NPR 19,550 in total, the Gazette minimum in force from Shrawan 1, 2082. No interest assumed.

  1. Employee PF: NPR 12,170 × 10% = NPR 1,217 a month, deducted from salary (Labour Act 2074 Section 52(1))
  2. Employer PF: NPR 12,170 × 10% = NPR 1,217 a month, paid on top of salary
  3. Deposited: NPR 1,217 + NPR 1,217 = NPR 2,434 a month, and NPR 2,434 × 12 = NPR 29,208 a year
  4. Balance after 10 years: NPR 29,208 × 10 = NPR 292,080, deposits only, with no interest assumed
  5. Your PF for the year: NPR 14,604 yours + NPR 14,604 the employer's = NPR 29,208
  6. Assessable income: NPR 234,600 gross + NPR 14,604 employer PF, which counts as your income (Income Tax Act 2058 Section 8(2)(f)) = NPR 249,204
  7. Income test: NPR 249,204 ÷ 3 = NPR 83,068
  8. Fixed ceiling: NPR 500,000 (Income Tax Act 2058 Section 63)
  9. Deduction: the lowest of the three, NPR 29,208
  10. Taxable income: NPR 249,204 − NPR 29,208 = NPR 219,996
  11. Income tax on that at the FY 2083/84 slabs: NPR 2,200 a year, NPR 183 a month in TDS
  12. With no PF on either side the tax on the gross alone would be NPR 2,346, so PF saves NPR 146 in tax this year

Balance from deposits after 10 years: NPR 292,080
NPR 30,000 basic, 20 years at 5.25%

A 60% basic on a NPR 50,000 salary, projected at the 5.25% the Fund states for FY 2082/83. A past year's rate used as an assumption, not a forecast.

  1. Employee PF: NPR 30,000 × 10% = NPR 3,000 a month, deducted from salary (Labour Act 2074 Section 52(1))
  2. Employer PF: NPR 30,000 × 10% = NPR 3,000 a month, paid on top of salary
  3. Deposited: NPR 3,000 + NPR 3,000 = NPR 6,000 a month, and NPR 6,000 × 12 = NPR 72,000 a year
  4. Assumed interest: 5.25% a year, worked monthly on the balance at the start of each month and credited once at the year end
  5. Year 1: NPR 72,000 deposited + NPR 1,733 interest = NPR 73,733
  6. Year 20: NPR 2,308,529 brought forward + NPR 72,000 deposited + NPR 122,930 interest = NPR 2,503,459
  7. After 20 years: NPR 1,440,000 deposited + NPR 1,063,459 interest = NPR 2,503,459, a projection at the assumed rate
  8. Your PF for the year: NPR 36,000 yours + NPR 36,000 the employer's = NPR 72,000
  9. Assessable income: NPR 600,000 gross + NPR 36,000 employer PF, which counts as your income (Income Tax Act 2058 Section 8(2)(f)) = NPR 636,000
  10. Income test: NPR 636,000 ÷ 3 = NPR 212,000
  11. Fixed ceiling: NPR 500,000 (Income Tax Act 2058 Section 63)
  12. Deduction: the lowest of the three, NPR 72,000
  13. Taxable income: NPR 636,000 − NPR 72,000 = NPR 564,000
  14. Income tax on that at the FY 2083/84 slabs: NPR 5,640 a year, NPR 470 a month in TDS
  15. With no PF on either side the tax on the gross alone would be NPR 6,000, so PF saves NPR 360 in tax this year

Projected balance after 20 years: NPR 2,503,459

NPR 150,000 a month, saving at 20%

NPR 100,000 basic on a NPR 150,000 salary, 25 years, no interest assumed. The deduction comes off the 20% band, so every rupee of PF saves 20 paisa of tax.

  1. Employee PF: NPR 100,000 × 10% = NPR 10,000 a month, deducted from salary (Labour Act 2074 Section 52(1))
  2. Employer PF: NPR 100,000 × 10% = NPR 10,000 a month, paid on top of salary
  3. Deposited: NPR 10,000 + NPR 10,000 = NPR 20,000 a month, and NPR 20,000 × 12 = NPR 240,000 a year
  4. Balance after 25 years: NPR 240,000 × 25 = NPR 6,000,000, deposits only, with no interest assumed
  5. Your PF for the year: NPR 120,000 yours + NPR 120,000 the employer's = NPR 240,000
  6. Assessable income: NPR 1,800,000 gross + NPR 120,000 employer PF, which counts as your income (Income Tax Act 2058 Section 8(2)(f)) = NPR 1,920,000
  7. Income test: NPR 1,920,000 ÷ 3 = NPR 640,000
  8. Fixed ceiling: NPR 500,000 (Income Tax Act 2058 Section 63)
  9. Deduction: the lowest of the three, NPR 240,000
  10. Taxable income: NPR 1,920,000 − NPR 240,000 = NPR 1,680,000
  11. Income tax on that at the FY 2083/84 slabs: NPR 96,000 a year, NPR 8,000 a month in TDS
  12. With no PF on either side the tax on the gross alone would be NPR 120,000, so PF saves NPR 24,000 in tax this year

Balance from deposits after 25 years: NPR 6,000,000

Sources

Last checked against the Fund's own pages. Tax figures are for FY 2083/84.

  • Employees Provident Fund, Provident Fund service page (कर्मचारी सञ्चय कोष): the 10% + 10% deposit, the FY 2082/83 rate of 4.25% plus 1% (5.25% in total), interest calculated monthly but credited annually, and the return of the interest and profit on retirement or on leaving. Read 5 November 2026.
  • Employees Provident Fund, interest rates: where the Fund publishes its current rates. On 5 November 2026 the Fund's home page listed a provident fund rate with no fiscal year or effective date, so this page does not quote it and the calculator opens at 0%.
  • Labour Act 2074, Nepal Law Commission text: Section 52(1) (provident fund, 10% of basic matched by the employer) and Section 53(1) (gratuity). Read 6 August 2026.
  • Income Tax Act 2058, Section 63: the retirement contribution deduction and its NPR 500,000 ceiling, confirmed unchanged for FY 2083/84 against ICAN's budget highlights on 5 August 2026.

This page states no PF deposit deadline and no tax on a payout: neither has been checked against an official text for it.

For the formula and a payslip example, read how PF is calculated in Nepal. For PF against SSF and CIT, read CIT vs PF vs SSF or use the SSF contribution calculator. For gratuity, read gratuity in Nepal. For running PF on every payslip, see NepalHRM payroll.

Using the calculator

Basic Salary In, Balance and Tax Out

PF is assessed on the basic component of a Nepali salary. The gross figure is only needed for the tax side, where the deduction is tested against income.

  1. 1

    Start from basic, not gross

    PF is 10% of basic remuneration, not of the whole salary. With a 60% basic, a NPR 50,000 salary has a basic of NPR 30,000, and the PF is NPR 3,000 a month from each side.

  2. 2

    Read the monthly and yearly split

    The employee's 10% is deducted from the salary. The employer's 10% is paid on top and never reduces take-home. Together they are 20% of basic, deposited to the employee's account at the Employees Provident Fund.

  3. 3

    Project the balance

    Choose the years and, if you want, an interest rate. At 0% the balance is the deposits alone. The Fund declares its own rate every year, so any rate you enter is an assumption and the result is a projection.

  4. 4

    Check the tax side

    Enter the gross salary. The calculator adds the employer's 10% to your income, applies the retirement deduction, the lowest of both shares together, one third of assessable income, or NPR 500,000, and shows the tax with PF and without it.

Last updated · Reviewed by Rajendra Regmi, Co-founder

PF or SSF

Provident Fund Against the Social Security Fund

An employer runs one or the other, never both. These are the lines that differ, all charged on basic salary.

LineProvident FundSocial Security Fund
Employee share10% of basic11% of basic
Employer share10% of basic20% of basic
Deposited each month20% of basic31% of basic
GratuitySeparate, 8.33% of basic a monthReplaced by the SSF contribution
1% social security tax on the first bandChargedWaived
Tax deductionWithin the shared retirement limitWithin the shared retirement limit
Held byEmployees Provident Fund (कर्मचारी सञ्चय कोष)Social Security Fund (सामाजिक सुरक्षा कोष)

The two are alternatives, not additions. An enterprise listed with the SSF contributes there and its staff run no separate PF line; outside it, the 10% + 10% PF usually runs with a voluntary CIT election alongside.

For which of the three leaves more take-home, with the arithmetic, read CIT vs PF vs SSF

PF and income tax

How the Retirement Deduction Treats Your PF

Section 63 of the Income Tax Act 2058, applied the way this site's salary tax calculator applies it, on the FY 2083/84 slabs.

01

Both shares count, and below the limit they cancel

The employer's 10% counts as your income (Section 8(2)(f) of the Act) and is deducted again with your own 10%. Below the limit the two cancel, so it is your own 10% that lowers the TDS taken every month.

02

Up to a limit, the lowest of three

The deduction is the lowest of the actual contribution, yours and the employer's together, one third of assessable income, or NPR 500,000. Past that limit another rupee of contribution still builds the balance; it stops reducing tax, and the employer's share above it is taxed as your income.

03

PF and CIT share the one limit

Contributions are counted together, not per fund, so PF, both shares of it, already uses part of the limit before any CIT is added. Model a CIT rate on a full salary with the salary tax calculator.

04

The saving is the band it comes off

A rupee of deduction saves tax at the rate of the band it comes off. The FY 2083/84 bands run 1%, 10%, 20%, 27%, 29%, so where taxable income sits inside the first band the saving is 1 paisa a rupee.

05

At retirement or when you leave

The Employees Provident Fund's own description: it manages the deposit and returns the interest and profit to the employee after retirement or on leaving the office for any reason, and it sends contributors a yearly statement of contributions, interest and balance. Tax on that payout is not worked out here.

06

Gratuity is a separate benefit

8.33% of basic a month under Labour Act 2074 Section 53(1), apart from the 10% + 10% PF under Section 52(1). The calculator shows the monthly gratuity and keeps it out of the PF balance.

One salary here · the whole payroll in the app

PF on Every Payslip, Without the Spreadsheet

This page works out one employee's PF. NepalHRM works it out for everyone, every month, from the same rates.

  • PF, CIT and SSF deductions are set once in payroll settings and applied to every employee on every run.
  • Each payslip shows the employee contribution as a deduction and the employer contribution separately.
  • Salary sheet and finance reports come out of the same run, so the deposit figure is not retyped.
  • Periods follow the BS fiscal year, so the contribution history lines up with the year you report on.
See how NepalHRM payroll works
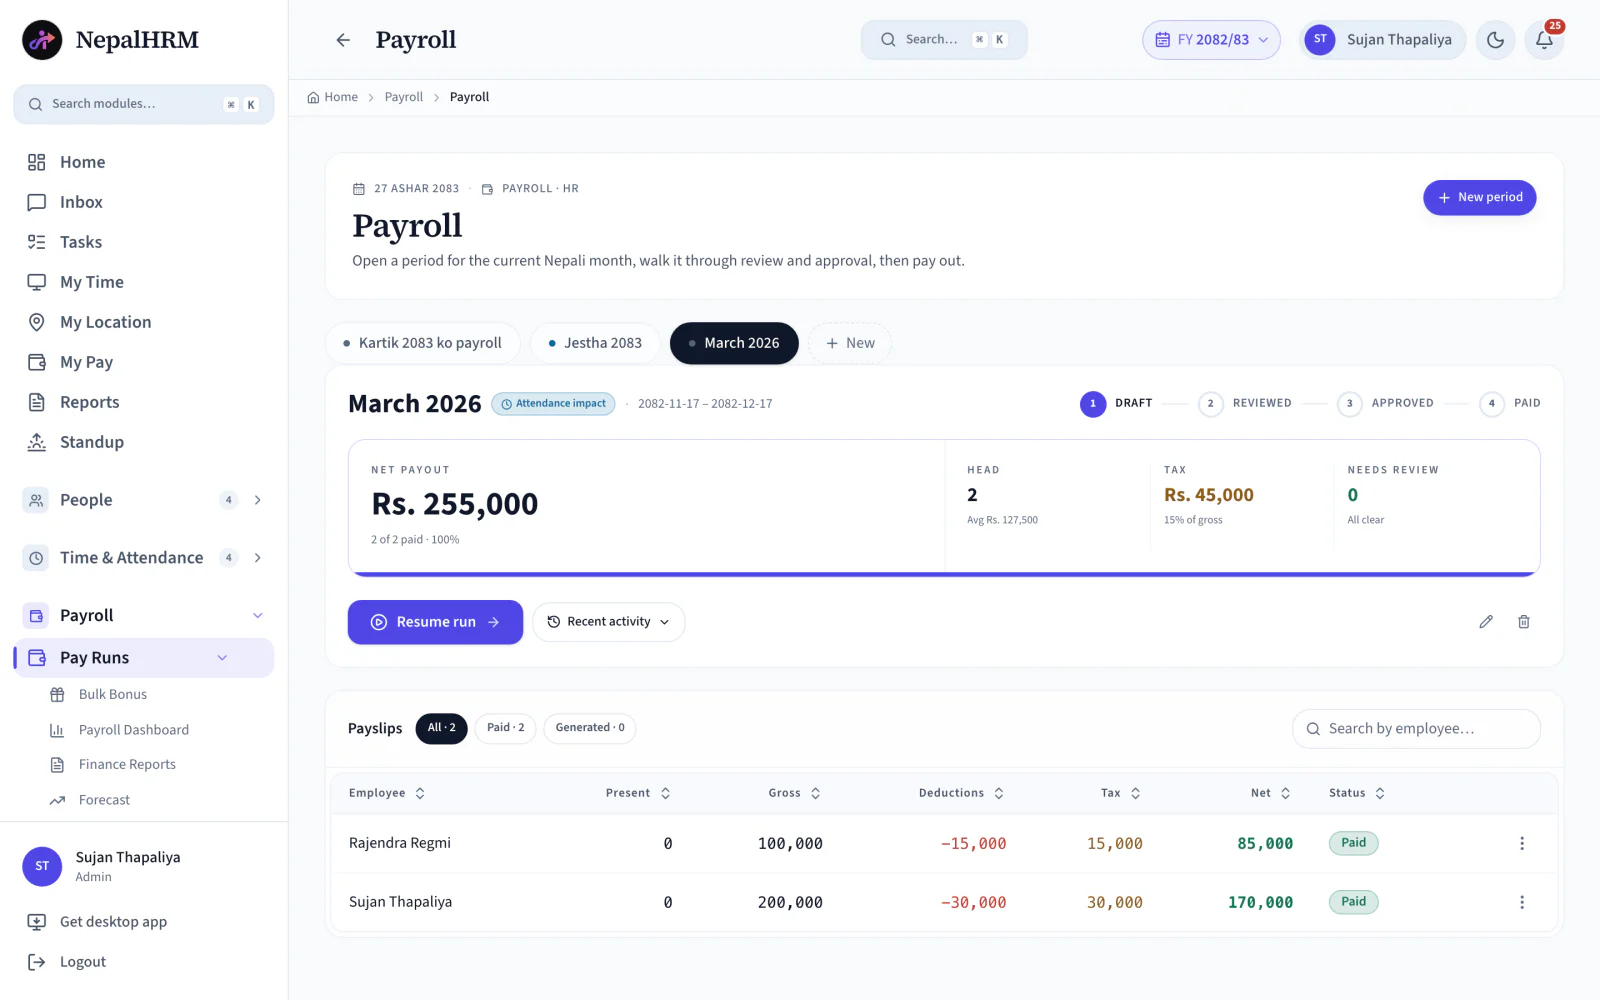
A NepalHRM payroll period with gross, deductions, tax and net pay listed for each employee, and the net payout and tax totals for the run.
FAQs

Provident Fund in Nepal, Answered

PF is 10% of basic salary from the employee and 10% from the employer, 20% in total, deposited every month to the employee's account at the Employees Provident Fund. On a NPR 30,000 basic that is NPR 3,000 from each side, NPR 6,000 a month and NPR 72,000 a year.

From basic salary. Both shares are calculated on the basic component only, so allowances and overtime do not change the PF figure.

On a NPR 30,000 basic the deposits alone come to NPR 720,000 after 10 years: NPR 6,000 a month for 120 months. Interest comes on top at whatever rate the Fund declares each year, which is why the calculator treats any rate as an assumption and calls the result a projection.

The Fund declares it each year. Its Provident Fund service page states that in FY 2082/83 contributors received 4.25%, with a further 1% added at the end of the year, 5.25% in total, calculated monthly but credited annually. That is a past year's rate. Check epf.org.np for the current one before relying on a projection. The calculator starts at 0% and offers the FY 2082/83 figure as a choice, not as a default.

Yes, within a limit. Under Section 63 of the Income Tax Act 2058 the retirement contribution deduction is the lowest of the actual contribution (your 10% and the employer's 10%, which also counts as your income), one third of assessable income, or NPR 500,000 a year. PF and CIT share that one limit.

No. It is paid on top of the salary and credited to the same PF account, so the balance grows by 20% of basic a month while take-home falls only by your own 10% and any TDS.

No. Gratuity is 8.33% of basic a month under Section 53(1) of the Labour Act 2074, a separate benefit from the 10% + 10% PF under Section 52(1). The calculator shows the monthly gratuity and keeps it out of the PF balance.

The Employees Provident Fund's own description is that it manages the deposit and returns the interest and profit to the employee after retirement or on leaving the office for any reason. This calculator does not work out the tax on that payout.

One or the other. An enterprise listed with the Social Security Fund deducts 11% and contributes 20% of basic there, and those employees run no separate PF. Outside the SSF it is the 10% + 10% PF, usually with a CIT election alongside it. An SSF contributor is also exempt from the 1% social security tax on the first income band.

कर्मचारी सञ्चय कोष (Karmachari Sanchaya Kosh) is the Employees Provident Fund, the body that holds the deposits. सञ्चय कोष (Sanchaya Kosh) on its own means provident fund.

Neither. PF and CIT share one deduction limit, and the salary tax calculator models a CIT rate on a full salary. This page also projects the same basic every month, so run it again with a higher basic to see what a raise does.

More free tools

While You're Here, Try These Too

Every NepalHRM tool is free, runs in your browser and needs no account. See all of the free Nepal payroll and tax calculators.

Let NepalHRM Run PF on Every Payslip

10% employee plus 10% employer, on every basic salary, every month. NepalHRM applies the contribution on each payslip and keeps the history by BS fiscal year.

  • PF on every payslip
  • CIT and SSF handled too
  • Free onboarding