NepalHRM
Free Gratuity Calculator

Gratuity Calculator Nepal: 8.33% of Basic, Month by Month

Enter the basic salary, the joining date and the last day in BS or AD, and whether the worker is in SSF. Read the gratuity (उपदान) for the period under Section 53 of the Labour Act 2074, with every line of the working shown.

  • Labour Act 2074, Section 53
  • BS or AD dates
  • Nothing leaves your browser

Labour Act 2074, Section 53

Of basic, every month
8.33%
No qualifying period
Day one
For SSF members
Inside 31%
To settle what is owed at exit
15 days
Social Security Fund
Changes where the money is, not the amount.
Service dates
Joining date
31 August 2022 AD
Last day of service
17 October 2026 AD
Gratuity a monthNPR 2,998.808.33% of basic · Section 53(1)
Months counted49.551,509 days, both ends included
Gratuity for the periodNPR 148,586In the worker's name at the Fund

The working

  1. Gratuity a month: NPR 36,000 basic × 8.33% = NPR 2,998.80 (Section 53(1)).
  2. Service counted: 15 Bhadra 2079 BS to 31 Ashwin 2083 BS, both days included, 1,509 days.
  3. 49 whole BS months × NPR 2,998.80 = NPR 146,941.20.
  4. Bhadra 2079, 17 of 31 days: NPR 2,998.80 × 17/31 = NPR 1,644.50.
  5. Total for 49.55 months: NPR 148,585.70.

Enrolled in SSF. This money goes into the Social Security Fund in the worker's name every month (Section 53(2)), inside the 31% contribution rather than on top of it (Section 57). At exit the worker claims it from the Fund; the employer owes only months not yet deposited, within 15 days (Section 148(1)), and has to help with the claim (Section 148(2)).

This assumes the same basic remuneration every month and no unpaid days. Basic includes the annual increment (Section 2(a)), so if it rose during the period, run each salary period separately and add them. A part month is counted by days served over days in that BS month, which is payroll practice: the Act sets the monthly rate and says nothing about part months.

Using the calculator

Four Inputs, Every Line of the Working

The calculator applies Section 53(1) to every Bikram Sambat month in the period, the way a Nepali payroll counts months, and prints each step so the total can be checked by hand.

  1. 1

    Enter monthly basic salary

    Basic, not gross. Section 53(1) is a share of basic remuneration, and Section 2(a) counts the increment that follows a year of employment as part of basic. If the basic changed during the period, run each salary period separately and add the results.

  2. 2

    Enter the joining date and the last day

    In BS or AD, whichever your records keep; the other calendar is shown underneath. Both days count. A joining date before 19 Bhadra 2074 is counted from that day, when the Act commenced (Section 53(4)).

  3. 3

    Say whether the worker is in SSF

    It does not change the amount. It changes where the money is: in the Social Security Fund in the worker's name, or with the employer to deposit as prescribed or pay out (Sections 53(3) and 53(6)).

  4. 4

    Read the working

    8.33% of basic for one month, the whole BS months, any part month at days served over days in that month, and the total. Each line is rounded to the paisa, so the lines add up to the total exactly.
Last updated · Reviewed by Rajendra Regmi, Co-founder

Gratuity rules in Nepal

Section 53, Clause by Clause

The rule as the Labour Act 2074 states it, from the consolidated text as amended through 2082. A collective agreement or a contract may give more; nothing may give less.

RuleWhat the Act saysSection
Rate8.33% of basic remuneration, every month53(1)
From when, and whereFrom the day the worker started work, deposited in the worker's name in the Social Security Fund53(2)
Before the Fund's law appliesDeposited as prescribed, until the Fund is operating or its law applies to that employer53(3)
Service before the ActOwed from 19 Bhadra 2074, the day the Act commenced, to a worker who was not owed gratuity before53(4)
Older balancesGratuity held in a retirement fund or by the employer is transferred to the Social Security Fund53(5)
Cannot be depositedPaid to the worker as an additional 8.33% of basic instead53(6)
Basic remunerationIncludes the increment that follows a year of employment2(a)
SSF contributorsNo further contribution for what the scheme already covers57
At exitEverything owed is paid within 15 days, and the employer helps the worker claim from the Fund148(1), 148(2)
Not depositedOn an application, the Labour and Employment Office can order the employer to pay it, with damages of double that amount163(2)(d)

Nothing in Section 53 sets a minimum period of service. The years-of-service formula with a qualifying period that is still quoted for Nepal came from the Labour Act 2048, which Section 183(1) repealed. Sub-section 53(7) of the original 2074 text was struck out in 2075, so the consolidated text runs to 53(6).

Why the monthly deposit replaced the old lump sum, and what an employer still holding gratuity on its own books has to do: Gratuity in Nepal, the full guide

How SSF changes it

In SSF or Not: What Changes, What Does Not

The 8.33% is the same either way. What changes is who holds it, and what is left to settle when the worker leaves.

01

The amount is the same

Section 53(1) sets 8.33% of basic a month whoever ends up holding it. SSF status decides where the money sits and what is owed at exit, not the figure, which is why the calculator gives the same total either way.

02

In SSF: it is inside the 31%, not on top

The Fund's operating procedure takes 11% from the worker and 20% from the employer, 31% of basic, and puts 28.33% of it into old-age protection. That is the 10% plus 10% provident fund of Section 52(1) and the 8.33% gratuity of Section 53(1), to the decimal. Section 57 then says an SSF contributor makes no further contribution for what the scheme covers.

03

In SSF: nothing separate at exit for deposited months

Months already deposited sit in the Fund in the worker's name (Section 53(2)) and are claimed from the Fund under its own rules. The employer settles any month not yet deposited within 15 days (Section 148(1)), and has to help the worker claim from the Fund (Section 148(2)).

04

Not in SSF yet: deposit as prescribed

Until the Fund's law applies to the employer, Section 53(3) has gratuity deposited as prescribed, and Section 53(5) moves what the employer has accumulated to the Fund once it does. The 8.33% runs from the first day either way.

05

Cannot be deposited: pay it to the worker

Where gratuity cannot be deposited under 53(2) or 53(3) for any reason, Section 53(6) has the employer pay the worker an additional 8.33% of basic. The obligation does not lapse because the deposit route is closed.

06

Two part-time employers: each pays

Section 21: a part-time worker with more than one employer gets gratuity, provident fund or other social security contributions from each of them, on the basic remuneration that employer pays.

Worked examples

Three Cases, Worked Line by Line

Computed by the same function as the calculator above. A part month is counted by days served over days in that BS month, which is payroll practice: the Act sets the monthly rate and is silent on part months.

A full year, enrolled in SSF

  • Basic salary: NPR 30,000 a month
  • Joined: 1 Shrawan 2082 BS (17 July 2025)
  • Last day: 32 Ashad 2083 BS (16 July 2026)
  • SSF: enrolled
  1. Gratuity a month: NPR 30,000 basic × 8.33% = NPR 2,499.00 (Section 53(1)).
  2. Service counted: 1 Shrawan 2082 BS to 32 Ashad 2083 BS, both days included, 365 days.
  3. 12 whole BS months × NPR 2,499.00 = NPR 29,988.00.
  4. Total for 12 months: NPR 29,988.00.

Gratuity: NPR 29,988.00, deposited month by month in the worker's name in the Fund (Section 53(2)).

Part months at both ends, not in SSF

  • Basic salary: NPR 45,000 a month
  • Joined: 15 Bhadra 2079 BS (31 August 2022)
  • Last day: 10 Kartik 2083 BS (27 October 2026)
  • SSF: not enrolled
  1. Gratuity a month: NPR 45,000 basic × 8.33% = NPR 3,748.50 (Section 53(1)).
  2. Service counted: 15 Bhadra 2079 BS to 10 Kartik 2083 BS, both days included, 1,519 days.
  3. 49 whole BS months × NPR 3,748.50 = NPR 183,676.50.
  4. Bhadra 2079, 17 of 31 days: NPR 3,748.50 × 17/31 = NPR 2,055.63.
  5. Kartik 2083, 10 of 30 days: NPR 3,748.50 × 10/30 = NPR 1,249.50.
  6. Total for 49.88 months: NPR 186,981.63.

Gratuity: NPR 186,981.63, to be deposited as prescribed or, where it cannot be, paid to the worker (Sections 53(3) and 53(6)).

Joined before the Act commenced

  • Basic salary: NPR 60,000 a month
  • Joined: 1 Baishakh 2072 BS (14 April 2015)
  • Last day: 31 Ashwin 2083 BS (17 October 2026)
  • SSF: enrolled
  1. Gratuity a month: NPR 60,000 basic × 8.33% = NPR 4,998.00 (Section 53(1)).
  2. Counting starts on 19 Bhadra 2074 BS, the day the Labour Act 2074 commenced (Section 53(4)). The 874 days before it are outside the 8.33% accrual.
  3. Service counted: 19 Bhadra 2074 BS to 31 Ashwin 2083 BS, both days included, 3,331 days.
  4. 109 whole BS months × NPR 4,998.00 = NPR 544,782.00.
  5. Bhadra 2074, 13 of 31 days: NPR 4,998.00 × 13/31 = NPR 2,095.94.
  6. Total for 109.42 months: NPR 546,877.94.

Gratuity under Section 53: NPR 546,877.94. Anything built up before 19 Bhadra 2074 under the old Act is a separate balance (Section 53(5)).

One worker here · the whole payroll in the app

The Contribution Gratuity Sits In, on Every Payslip

For SSF-enrolled staff the 8.33% travels inside the 31% contribution. NepalHRM works that contribution out on basic for every employee on every payroll run, so the deposit figure is never retyped.

  • SSF is computed at 11% employee and 20% employer of basic on every payroll run, and both sides appear on the payslip.
  • PF, CIT and SSF deductions are set once in payroll settings and applied to every employee on every run.
  • Salary sheet and finance reports come out of the same run, so the deposit figure is not retyped.
  • Periods follow the BS fiscal year, so the contribution history lines up with the year you report on.
See how NepalHRM payroll works
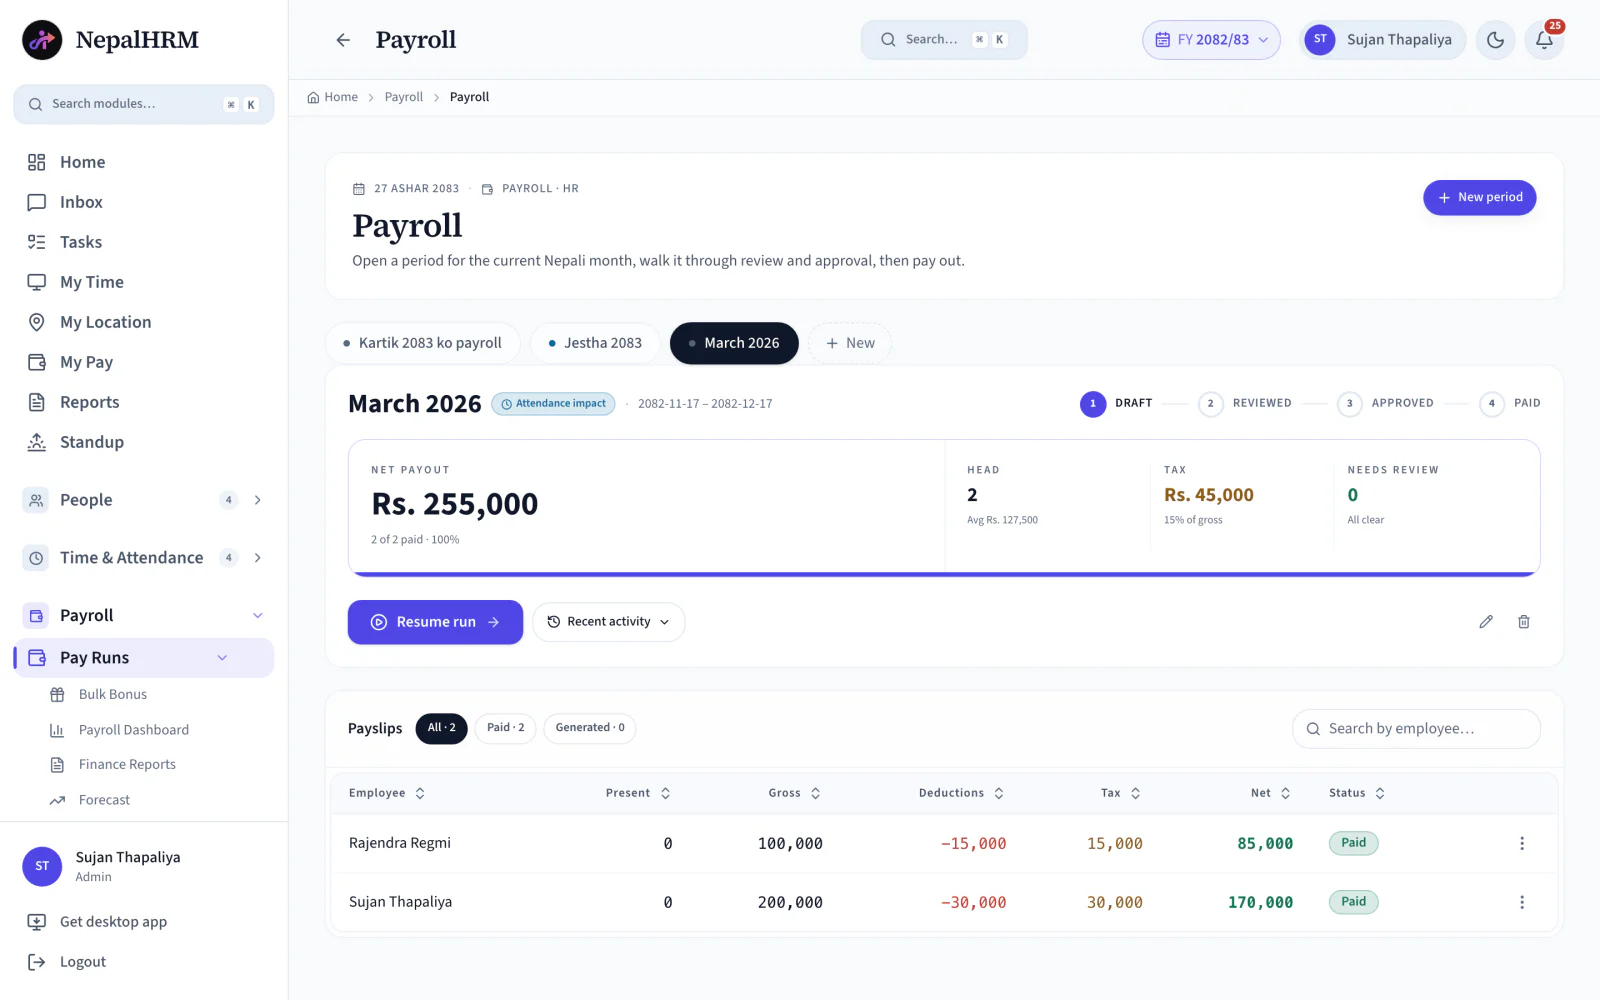
A NepalHRM payroll period with gross, deductions, tax and net pay listed for each employee, and the net payout and tax totals for the run.
FAQs

Gratuity in Nepal, Answered

Section 53(1) of the Labour Act 2074 sets gratuity at 8.33% of basic remuneration every month, and Section 53(2) runs it from the day the worker started work. Multiply the monthly basic by 8.33%, then by the months served. Twelve months of it are 99.96% of one month's basic, which is why it is often described as one month's basic for each year of service.

They are Section 53 of the Labour Act 2074: 8.33% of basic every month (53(1)), deposited in the worker's name in the Social Security Fund from the first day of work (53(2)), or as prescribed until the Fund's law applies to that employer (53(3)), owed from the day the Act commenced to anyone not owed it before (53(4)), with older balances moved to the Fund (53(5)), and paid to the worker if it cannot be deposited (53(6)). Section 57 stops an SSF contributor paying it twice.

No. Nothing in Section 53 sets one, and 53(2) applies it from the very day the worker started work, so a worker who leaves after eight months has eight months of gratuity. The rule that tied gratuity to years of service with a qualifying period came from the Labour Act 2048, which Section 183(1) of the 2074 Act repealed.

On basic. Section 53(1) says basic remuneration, and Section 2(a) defines that separately and includes in it the increment that follows a year of employment. Allowances stay out of it, and the base rises with each annual grade.

Not for months already deposited. Under Section 53(2) that money is in the Fund in your name, and you claim it from the Fund under its own rules. What the employer owes at exit is anything not yet deposited, within the 15 days Section 148(1) allows, and Section 148(2) obliges the employer to help you obtain what the Fund pays.

Not in the 8.33% figure. Section 53(4) owes gratuity from the day the Act commenced, 19 Bhadra 2074 (4 September 2017), to a worker who was not owed it before, so the calculator starts counting there. Gratuity accumulated earlier under the repealed Labour Act 2048 was to be transferred to the Social Security Fund under Section 53(5), as a separate balance this calculator does not compute.

Upadan (उपदान). Section 53 of the Labour Act 2074 is headed उपदान पाउने, the right to receive gratuity.

Sources

Last checked · FY 2083/84

Stop Working Out Gratuity One Employee at a Time

This calculator settles one person's months. NepalHRM computes the SSF contribution the gratuity sits inside for every employee on every run, on basic, and shows both sides on the payslip.

  • SSF on every payslip
  • PF & CIT handled too
  • BS fiscal year periods
  • Free onboarding